Startup Booted Financial Modeling: How to Plan Cash, Costs, and Sustainable Growth
A practical framework for self-funded founders who need realistic revenue forecasts, cash visibility and better financial decisions without relying on another funding round.

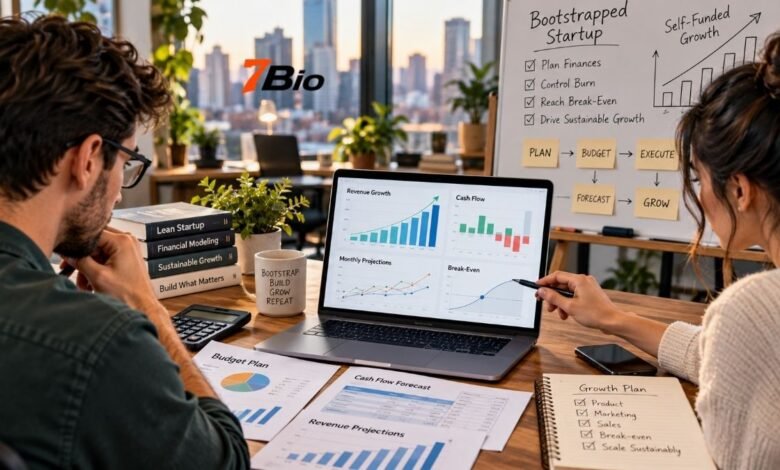
Startup Booted Financial Modeling is a practical way to forecast a startup’s finances that depends primarily on founder capital, customer revenue, and reinvested earnings rather than assuming regular injections of outside investment.
The wording “startup booted” is informal; in practice, the idea is better understood as financial modeling for a bootstrapped or self-funded startup. The model connects assumptions about sales, pricing, operating costs, hiring and payment timing to the questions founders actually need answered: How much cash will remain? When could the business reach break-even? Can it afford another employee? What happens if sales arrive later than expected?
For a self-funded company, these questions matter because another investment round cannot automatically fix an unrealistic forecast. A useful model therefore focuses less on producing impressive long-term numbers and more on helping the founder understand the financial consequences of everyday business decisions.
Quick Answer
Startup Booted Financial Modeling means building a financial forecast around realistic revenue, costs, cash movements, and available resources for a bootstrapped startup. Its purpose is not to predict the future perfectly. It shows how different assumptions could affect cash, profitability, hiring capacity, and growth.
What Is Startup Bootstrapped Financial Modeling?
A financial model is a structured representation of how a business expects to earn and spend money over time.
For a bootstrapped startup, the model usually starts with the resources already available to the company rather than assuming future funding will cover a shortfall.
A practical model can include:
- customer and sales assumptions;
- pricing and revenue forecasts;
- direct and operating costs;
- salaries and future hiring;
- cash receipts and payment timing;
- profit and loss projections;
- cash flow forecasts;
- break-even calculations;
- expected capital expenditure;
- scenario analysis.
The exact structure depends on the business. A subscription software company, online retailer, and consulting business will not need identical models because their revenue timing, margins, payment terms, and operating costs differ.
The goal is therefore not to copy a universal spreadsheet. It is to create a model that reflects how the particular company actually operates.
Why Financial Modeling Matters More When a Startup Is Bootstrapped
A company can increase spending rapidly when it has substantial committed financing. A self-funded startup normally has less room for forecasting errors.
That makes cash timing especially important.
A sale appearing in an income forecast does not necessarily mean the cash has arrived in the bank. A business might issue an invoice today and receive payment several weeks later while wages, hosting bills, suppliers, or rent must be paid sooner.
This difference explains why a profitable-looking forecast can still hide a cash shortage.
A good Startup Booted Financial Modeling process therefore examines both economic performance and actual cash movement.
Profit and Cash Are Different Questions
Profitability asks whether revenue exceeds relevant costs over an accounting period.
Cash flow asks when money actually enters and leaves the business.
Both matter, but founders should not treat them as interchangeable.
For example, imagine a small business completes £20,000 of work in one month, but most clients pay the following month. If payroll and supplier bills are due immediately, the company may still face a short-term cash problem despite having earned revenue.
That is why payment timing deserves its own place in the model.
Build the Model From Business Drivers
One of the strongest ways to improve a forecast is to start with operational drivers rather than choosing a desired revenue figure and working backward.
For example, revenue for a subscription business might depend on:
Active customers × average monthly revenue per customer
A service business might instead use:
Billable projects × average project value
An ecommerce company may need:
Orders × average order value
The correct driver depends on how the business earns money.
Step 1: Define the Starting Position
Begin with known information:
- current cash balance;
- existing customers;
- current monthly revenue;
- confirmed recurring expenses;
- employee and contractor costs;
- debts or contractual commitments;
- known payment schedules.
Separating known figures from assumptions makes the model easier to audit later.
Step 2: Create a Revenue Forecast
Connect revenue assumptions to measurable drivers wherever possible.
Rather than simply forecasting that sales will double, identify what would have to happen for that growth to occur.
Possible drivers include:
- number of leads;
- conversion rate;
- active customers;
- customer retention;
- selling price;
- transaction frequency;
- available delivery capacity.
Early-stage businesses have limited historical data, so forecasts naturally contain uncertainty. The answer is not to pretend that uncertainty disappears. It is to make the assumptions visible.
Model Costs Properly
A revenue forecast alone is not a financial model.
Founders also need a realistic view of what the business must spend to generate and support that revenue.
Fixed and Semi-Fixed Costs
These may include:
- salaries;
- software subscriptions;
- rent;
- insurance;
- accounting;
- professional services.
Some costs described as fixed may eventually change as the company grows, so the model should reflect when those changes are expected.
Variable Costs
Variable costs generally change with activity.
Examples may include:
- payment processing;
- shipping;
- product materials;
- marketplace commissions;
- usage-based infrastructure;
- sales commissions.
Identifying these costs helps the founder understand contribution margin and whether additional sales actually improve the financial position.
Cash Flow Should Be a Core Part of the Model
For a bootstrapped company, a cash flow forecast is often one of the most useful parts of the entire model.
It should show, period by period:
| Model Component | Main Question |
|---|---|
| Opening cash | How much cash is available at the start? |
| Cash receipts | When is money actually expected to arrive? |
| Cash payments | When must expenses actually be paid? |
| Net cash movement | Did available cash increase or decrease? |
| Closing cash | How much remains after the period? |
The timing interval can be monthly for normal planning, although a business facing tight liquidity may need a more detailed view.
The model should reflect real payment behavior rather than assuming every invoice is paid immediately.
Understand Burn Rate and Runway
Burn rate commonly describes how quickly a loss-making startup consumes cash.
A simple form of net cash burn can be viewed as:
Cash paid out − cash received during the period
When net burn is positive and relatively stable, runway can be estimated as:
Available cash ÷ average net monthly burn
For example, if a company has £60,000 in available cash and its current net cash burn is £6,000 per month, a simple calculation suggests around 10 months of runway.
That figure is only an estimate. It becomes less reliable when revenue, expenses, or working-capital requirements change significantly from month to month.
A useful model therefore forecasts the cash balance directly, rather than relying exclusively on one runway number.
Include Break-Even Analysis
Break-even analysis helps answer when revenue or sales volume may become sufficient to cover costs.
For a business selling one relatively consistent product, a simplified unit calculation is:
Break-even units = Fixed costs ÷ Contribution per unit
where:
Contribution per unit = Selling price − Variable cost per unit
Real businesses can be more complicated because they may sell several products with different margins or have costs that change in steps.
Even so, break-even analysis gives founders a useful decision framework. Instead of asking only, “How fast can we grow?”, they can ask, “What level of activity would allow the business to support itself?”
Use Scenarios Instead of One Perfect Forecast
No founder knows exactly what future sales will be.
That’s why scenario planning is more useful than pretending a single projection is certain.
A practical Startup Booted Financial Modeling workbook might contain three cases:
Base Case
The most reasonable planning scenario using current evidence and expected performance.
Downside Case
A more cautious scenario in which sales arrive more slowly, customers pay later, costs increase, or another important assumption deteriorates.
Upside Case
A stronger scenario showing what happens if selected business drivers perform better than expected.
These scenarios aren’t valuable for the labels themselves. Their purpose is to expose which assumptions materially affect the company’s cash position.
Model Hiring Before Making the Commitment
Hiring can create a high ongoing cost for a small startup.
Before adding a role, the model should incorporate more than the headline salary. Depending on the location and employment arrangement, additional costs can include employer obligations, benefits, recruitment expenses, equipment, software, and onboarding.
The financial question should not simply be:
“Can we pay this employee next month?”
A stronger question is:
“How does this hire affect the company’s cash position across several months under realistic revenue scenarios?”
This turns the financial model into a decision tool rather than a historical record.
Compare Forecasts With Actual Results
A financial model loses much of its usefulness if you create it once and then ignore it.
At regular intervals, compare:
Forecast → Actual result → Difference → Explanation → Updated assumption
Suppose the company forecast 100 new customers but acquired only 70. The important task is not simply to replace the number. The founder should understand why the result differed.
Was traffic lower?
Did conversion decline?
Was the sales cycle longer?
Did capacity limit delivery?
This process gradually replaces guesses with operating evidence.
Common Startup Financial Modeling Mistakes
Building Revenue From Market Size Alone
A large market does not automatically produce customers.
A forecast becomes more useful when it connects revenue to acquisition capacity, conversion, pricing, and retention.
Ignoring Payment Delays
Revenue recognized and cash received may occur at different times. The model should reflect expected collection timing.
Forgetting Taxes and Statutory Costs
Taxes and employment-related obligations vary by jurisdiction and company circumstances. Founders should obtain appropriate accounting or tax guidance instead of using generic assumptions for material decisions.
Assuming Costs Stay Constant During Growth
Growth can create additional staffing, software, infrastructure, and fulfillment requirements. These should enter the model when the operational trigger occurs.
Treating the Forecast as a Promise
A financial model is a planning framework built from assumptions, not a guarantee of future results.
Making the Spreadsheet Too Complicated
A complex workbook is not automatically more accurate.
A model should be detailed enough to support decisions while remaining understandable enough to update consistently.
A Practical Monthly Review Checklist
A founder reviewing the model can ask:
- How much unrestricted cash is currently available?
- Which major payments are due next?
- Are customers paying when expected?
- How did actual revenue compare with the forecast?
- Which expense categories exceeded assumptions?
- Has the expected break-even point changed?
- What happens to cash under a weaker sales scenario?
- Can planned hiring or expansion still be supported?
- Which assumption has the greatest financial impact?
- What should be updated before the next review?
These questions keep attention on decisions rather than spreadsheet complexity.
FAQs
What is Startup Booted Financial Modeling?
It is financial modeling for a bootstrapped or primarily self-funded startup. It forecasts revenue, expenses, cash, and other financial outcomes so founders can understand how operating decisions may affect the business.
Is Startup Bootstrapped Financial Modeling only for technology companies?
No. The underlying approach can be useful for many self-funded businesses. However, the revenue drivers, cost structure, and level of detail should match the actual business model.
Can Excel or Google Sheets be used for startup financial modeling?
Yes. Many early-stage businesses can build a useful model in an ordinary spreadsheet. More specialized software may become helpful when reporting requirements, integrations, entities, or operational complexity increase.
How often should a startup update its financial model?
There is no universal schedule for every company, but review the model often enough that important decisions are based on current information. Monthly forecast-versus-actual reviews are a practical starting point for many businesses, while tighter cash situations may justify more frequent cash monitoring.
What is the most important part of a bootstrapped startup model?
No single component replaces the others, but cash visibility matters most because the business must remain able to meet its obligations as it grows.
Does a financial model guarantee that a startup will succeed?
No. A model depends on assumptions and cannot remove business uncertainty. Its value lies in showing the possible financial consequences of those assumptions before making decisions.
Final Takeaway
Startup Booted Financial Modeling is most useful when it remains practical.
A founder does not need the largest spreadsheet or the most optimistic five-year forecast. The useful model clearly connects customers, pricing, costs, payment timing, hiring, and growth decisions to profitability and available cash.
Build the first version from the information you genuinely know. Separate facts from assumptions. Test weaker scenarios. Compare forecasts with real results. Then update the model as the business generates better evidence.
For a self-funded startup, that discipline can turn financial modeling from a reporting exercise into an everyday management tool.